Capital Markets
Professionals
LFS programmes promote confidence, performance and profitability.
Excel with our faculty’s cutting-edge knowledge, practical exercises and workshops.
Leave LFS with a deep understanding, ready to deliver exceptional results.
Choose public courses below or tailored in-house delivery.
Choose your learning style
Enjoy the personal connection of small-group learning in our London classroom or
the convenience of live online learning delivering the same world-class teaching to your desktop.Â
Our courses
Please contact us to discuss specific times.
Accounting and Capital Requirements
+Asset Management
+Corporate Finance
+Derivatives and Structured Products
+Econometrics and Mathematics
+Financial Market Regulation
+Financial Markets
+Fintech and Artificial Intelligence
+Liquidity and Risk Management
+Macro Products (Bonds, FX, Commodities)
+Micro Products (Equities and Credit)
+Quantitative Techniques and Modelling
+Choose your time zone
Learn in London or remotely anywhere in the world.
Experienced advisors, with extensive knowledge of course content, can
help you choose the programme best suited to your needs.
Teaching Faculty
Our world-renowned teachers are first class communicators and acknowledged experts in their fields. They combine extensive practical experience with profound theoretical understanding.
Mayank Agrawal
Mayank Agrawal is a financial technology and AI specialist with more than 20 years of experience developing and deploying AI-driven solutions across financial markets. His expertise spans artificial intelligence and machine learning, systematic trading, quantitative investment strategies, risk analytics, and cloud-based financial platforms. May...ank was the Founder and CTO of IntelliBonds, where he developed AI-powered investment strategies and a portfolio optimisation framework using advanced neural networks and cloud technologies. He has also held senior technology and quantitative roles at Citi, Bloomberg, and other global financial institutions, working on projects spanning real-time risk analytics, algorithmic trading, and AI-driven credit rating prediction. His expertise includes AI/ML model development, systematic trading strategies, quantitative finance, and the application of advanced technology to investment and risk management. Mayank holds an Executive MBA in Strategy and Finance from London Business School and a Master’s degree in Computer Science from Banaras Hindu University. Mayank holds an Executive MBA in Strategy & Finance from London Business School and a Master’s degree in Computer Science from Banaras Hindu University.
Simon Acomb
Dr Simon Acomb has over 30 years of experience in quantitative finance. He started his career in finance at Barclays deZoete Wedd in 1992 in the Equities Derivatives Group and progressed to run the quantitative research team. This was followed by five years at Commerzbank, where he established a derivatives proprietary trading team and then beca...me head of the equity quantitative research group. Most recently, Simon has been a managing director at Morgan Stanley as global head of the Equities Analytic Modelling Group. He now works as a consultant and trainer in mathematical finance.
Jaime Arguello
Jaime Arguello is a senior investment and wealth management executive with over 35 years of experience across asset management, private banking, multi-asset investing and third-party manager selection. He most recently served as Global Chief Investment Officer at Architas, AXA Group’s multi-manager platform, where he led a team of investment profes...sionals overseeing around €30bn in multi-asset fund solutions across Europe and Asia. Prior to Architas, Jaime was Managing Director, Global Head of Multi-Management and Third-Party Fund Selection at Barclays Wealth in London. There he managed Barclays’ multi-asset fund range and manager-of-managers funds representing £10.5bn in assets, and oversaw a £7bn third-party mutual fund platform across long-only and alternative strategies for affluent and HNW clients. Earlier, at Pictet & Cie in Geneva, he headed third-party manager selection for Pictet Wealth Management and previously led a 30-person fixed income team. Jaime began his career in fixed income and capital markets roles at leading French institutions, and later founded a multi-management boutique focused on Latin American equity solutions for European investors. He holds an Engineer Degree in Economy-Finance from École Nationale des Ponts et Chaussées in Paris and is fluent in French, English and Spanish.
Katia Babbar
Katia Babbar holds a BSc in Mathematics from University College London and a PhD in Stochastic Analysis from Imperial College. With over 20 years of experience in the financial industry in the City of London, she has held leadership positions at UBS, Citi, and Lloyds Banking Group, overseeing FX Derivatives Quant Research teams and e-FX Algo Tradin...g as a Managing Director. As a Visiting Lecturer at the University of Oxford, Katia teaches courses on Statistics Financial Data Analysis and Decentralized Finance for the MSc in Mathematical and Computational Finance program. She is also a co-founder of Immersive Finance, a prominent FinTech company specializing in institutional-grade risk management and alpha generation for Digital Assets.
Enrique Benito
Enrique Benito is a senior risk management professional at a major global bank in London with first hand experience on collateral management and optimisation, treasury, ALM and regulatory matters. His past experience spans consulting at a big 4 auditing firm, where he advised financial institutions on implementation of collateral management framewo...rks and liquidity and capital requirements, and roles at GE Capital Bank, the Central Bank of Spain and the former UK Financial Services Authority where he was involved on the development and implementation of the Basel III framework. Enrique holds a PhD in Economics from City, University of London.
Werner De Bondt
Dr Werner F.M. De Bondt is director of the Richard H. Driehaus Center for Behavioral Finance at De Paul University in Chicago and one of the founders of the field of behavioral finance. Between 1992 and 2003, he was the Frank Graner Professor of Investment Management at the University of Wisconsin-Madison. Dr De Bondt studies the psychology of i...nvestors and financial markets. His research is interdisciplinary. He has examined key concepts of bounded rationality, e.g., people's tendency to exaggerate the true impact of new information, their bent towards wishful thinking, or their biased perceptions of risk. Dr De Bondt is a frequent speaker to academics and investment professionals around the world and his research articles have appeared in many scholarly journals. He holds degrees in economics, engineering, and public administration, as well as a Ph.D. in Business Administration from Cornell University (1985).
Seppe vanden Broucke
Dr Seppe vanden Broucke currently works as an assistant professor at the department of Decision Sciences and Information Management at KU Leuven. His research interests include business data mining and analytics, machine learning, profit driven analytics, fraud analytics, process management and process mining. His work has been published in renowne...d international journals and presented at top conferences. Dr vanden Broucke received a PhD in Applied Economics at KU Leuven, Belgium in 2014 after obtaining a Master’s degree (magna cum laude) in Business Economics: Information Systems Engineer from the same institution.
David Cox
Dr David Cox is a financial markets expert and educator with extensive practical experience in the financial markets and an international reputation for teaching advanced financial markets programmes. He spent 10 years in banking, primarily with Bank of America Capital Markets, before joining London Business School, where he established the financi...al markets seminar programme and combined research with teaching and consultancy. David is the Founding Director of London Financial Studies and specialises in quantitative techniques, interest rates, inflation, risk management, and derivative products. He was a member of the executive education faculty of ICMB in Geneva, now the Swiss Finance Institute, for 14 years and continues to design and deliver programmes for professionals and their clients at leading financial institutions, as well as for government organisations in the UK and United States.
Dan Crisan
Dan Crisan is Professor of Mathematics at Imperial College London, specialising in stochastic analysis and its applications to engineering and finance. His research focuses on stochastic and deterministic partial differential equations, backward stochastic differential equations, nonlinear filtering, and numerical methods for stochastic systems. ... He has published more than 30 research articles in international academic journals. His current work includes the development of high-order numerical algorithms and particle methods for the analysis and approximation of complex stochastic systems, with applications across mathematics, engineering, and financial modelling.
Zareer Dadachanji
Dr Zareer Dadachanji is a quantitative finance expert and consultant with more than 30 years of industry experience across multiple asset classes. His expertise spans the modelling of FX and equity derivatives, anti-fraud analytics, private equity fund modelling, and the development of AI-driven investment strategies. Zareer spent 13 years as a... front-office quant at leading banks and hedge funds, including NatWest/RBS, Credit Suisse, and Standard Chartered Bank, where he held senior quantitative roles and ultimately served as Global Head of FX Quants. His experience combines hands-on quantitative modelling with broad expertise across global cross-asset businesses. He is the Founder and Director of Model Quant Solutions, an independent consultancy providing bespoke quantitative analysis and modelling solutions to financial institutions and other clients. He is also the author of FX Barrier Options: A Comprehensive Guide for Industry Quants, published as part of the Palgrave Macmillan Applied Quantitative Finance series. Zareer holds a Triple First in Natural Sciences and a PhD in Computational and Theoretical Physics, both from the University of Cambridge.
Toon Daenen
Toon Daenen holds a Master's degree in Business Engineering from the prestigious Solvay Business School (VUB). He utilizes his academic background to make substantial contributions to the field. Toon plays a pivotal role in spearheading the development and management of the PRIIPs KID and ESG (SFDR/EET/...) cutting-edge solution that aligns with in...dustry standards and regulatory compliance. Currently, with his expertise and unwavering dedication, Toon significantly bolsters growth and success at RiskConcile.
Richard Fedrick
Richard Fedrick teaches courses globally in all areas of finance with a particular emphasis on interest rates and FX, derivatives, exotic options, structured products and risk management. He started his career in 1988 in the Derivatives Product Group at Morgan Stanley, which he joined after three years of post-graduate research in Theoretical Physi...cs. He spent three years as a rates and FX structurer at Morgan Stanley before moving to Deutsche Bank in London, where he joined a newly-formed team designing and selling structured products across Europe. In 1993 Richard joined General Re Financial Products, a AAA-rated derivatives boutique that rapidly became established as one of the world’s leading derivatives trading operations. At GRFP, Richard initially ran the structuring desk, before moving into trading (rates and FX exotics), and finished as a Managing Director and global co-head of structuring and sales. He joined Dresdner Kleinwort Wasserstein in 2002 before moving into the executive education industry in 2004. Richard has a 1st Class degree in Physics from St John’s College, University of Oxford.
Ignace Fets
Ignace Fets is currently a senior risk management professional at RiskConcile, a risk management advisory firm based in Belgium. Next to holding a master’s degree in Mathematics, he also obtained a master’s degree in Financial and Actuarial Engineering at the Catholic University of Leuven. He started his career as a big four risk advisory consu...ltant, where he was mainly working on credit risk, Basel capital requirements, solvency II and derivatives valuations. As a certified Financial Risk Manager (FRM), he performs risk advisory projects for some major London based hedge funds. He combines market, credit and liquidity risk calculations with a software suite including Python, Neo4j, PostgreSQL and AWS.
Helyette Geman
Dr Helyette Geman is a leading academic in quantitative finance, specialising in commodities, energy markets, mathematical finance, and financial engineering. She is Director of the Commodity Finance Centre at Birkbeck, University of London, and Research Professor at Johns Hopkins University. Helyette has published more than 140 papers in inter...national journals and is the author of several books on commodities and financial risk. She has advised financial institutions, commodity exchanges, and energy and mining companies on financial modelling and risk management. In 2022, she was named Financial Engineer of the Year by the International Association for Quantitative Finance (IAQF) and Northfield Financial. She holds PhDs in Probability and Finance, as well as graduate degrees in Mathematics and Theoretical Physics.
Jon Gregory
Dr Jon Gregory is an independent expert specialising in counterparty credit risk and related areas, including CVA, FVA, collateral, regulatory capital, initial margin, and central clearing. He has more than two decades of experience across a broad range of credit risk disciplines, having previously held senior positions at Barclays Capital, BNP Par...ibas, and Citigroup, and served as a consultant to the World Bank Group. Jon is a Senior Advisor to Solum Financial Derivatives Advisory and a faculty member of the Certificate in Quantitative Finance. He is widely recognised as a leading expert and pioneer in the application of quantitative methods to counterparty and credit risk. He is the author of The xVA Challenge: Counterparty Risk, Funding, Collateral, Capital and Initial Margin, now in its fifth edition, and Central Counterparties: The Impact of Mandatory Clearing and Bilateral Margin Requirements on OTC Derivatives, both published by Wiley Finance. Jon holds a PhD from the University of Cambridge.
Scott Henderson
Scott Henderson holds degrees in Economics and Psychology, laying the foundation for his successful career in financial markets compliance, risk, and governance. With over 20 years of experience in Investment Banking, Scott began his professional journey by trading Precious Metals and FX Options in London and Hong Kong. Throughout his career, he ha...s taken on various roles in Surveillance, addressing the risk of Market Abuse, Money Laundering, and Unauthorised Trading. Driven by his educational background, Scott has developed a keen interest in studying the risk-taking personalities of traders, investigating the relationship between corruption and economic performance, and leveraging data science to enhance surveillance practices.
Marc Henrard
Dr Marc Henrard is an independent expert specializing in interest rate modelling and risk management, and a visiting professor at University College London. Over the last 20 years, Marc has worked in various areas of quantitative finance. His experience includes management positions in risk management, trading, software development and quantitativ...e research. He previously worked as Global Head of Interest Rate Modelling for Dexia Group, Deputy Head of Treasury Risk at the Bank for International Settlements (BIS), and Head of Quantitative Research and Deputy Head of Interest Rate Trading also at BIS. Marc's research focuses on interest rate modelling, risk management and their efficient implementation. More recently, he has focused his attention to market infrastructure (CCP and bilateral margin, exchange traded product design, regulatory costs). He publishes on a regular basis in international finance journals, and is a frequent speaker at academic and professional conferences. Marc is the author of the books "The multi-curve framework: foundation, evolution and implementation" and "Algorithmic Differentiation in Finance Explained". Marc holds a PhD in Mathematics from the University of Louvain, Belgium. He has been a research scientist and university lecturer in Belgium, Italy, Chile and the United Kingdom.
Andre Horovitz
Andre Horovitz is the Founder of Financial Risk Fitness and has over 25 years of experience in the financial services industry. Mr Horovitz started his banking career at Lehman Brothers, where he was responsible for pricing, developing hedging strategies and marketing exotic interest rate derivatives. He subsequently held senior executive positions... at Oliver, Wyman & Co., Commerzbank, HVB Group (currently part of Unicredit), Nagler & Company and was Chief Risk Officer at Erste Bank and Credit Suisse. He is a frequent speaker at conferences and a contributor to various industry journals. His areas of expertise cover all classes of financial risk management including overall institutional strategy. Mr Horovitz holds an Engineering Diploma in Hydraulics from The Technical University Bucharest and an MBA in Finance from Stern Business School. He is also a certified GARP Financial Risk Manager (FRM).
Ruben Kerkhofs
Ruben Kerkhofs is a data scientist working at Riskconcile. Ruben holds a Master’s degree in Statistics and Data Science (KU Leuven) and a Bachelor’s degree in Business and Information Systems Engineering (Hasselt University). He currently pursues a PhD in Financial Mathematics at the KU Leuven where he studies the impact of climate change on financ...ial markets and the development of climate stress tests. Ruben teaches courses on data management and analytics to graduate students from the KU Leuven and has been a speaker and workshop host at leading research institutions and business schools.
Peter Leoni
Dr Peter Leoni graduated with a PhD in mathematical physics and started his professional career in Belgium, where he worked for KBC Asset Management as a risk manager modelling equity and interest rate derivatives. He then moved to ING as a front office quant on the exotic equity derivatives desk; and before the credit crunch hit, Dr Leoni reali...zed that energy modelling had a lot of unsolved issues and decided to change his career path towards commodities, focusing on energy. Dr Leoni then spent 4 years in the trading unit of GDF Suez in Brussels, working thereafter for a private fund in Geneva and Macquarie Bank in London. He is currently the director of trading for the London/Geneva office of a privately owned trading firm. He holds a position of visiting professor for the Catholic University of Leuven in Belgium since 2011 and has published several articles on modelling, pricing and hedging derivatives in equity and commodities markets. In 2014, Dr Leoni published the book “Hedging and the Greeks Explained”.
Henrik Lumholdt
Henrik Lumholdt is a finance professional with more than 30 years of capital markets experience. He is a Partner at Copenhagen Allocation Partners and previously served at BBVA Asset Management, Bank of America Spain, FG/Merrill Lynch, and Nordea Bank. Henrik has been an Adjunct Professor of Finance and Economics at IE Business School since 200...1, where he has received numerous teaching awards. He is the author of Strategic and Tactical Asset Allocation: An Integrated Approach and holds degrees in Economics from Copenhagen Business School.
Naina Patel
Naina Patel is a trained lawyer with over 20 years of experience in international banking and structured finance transactions, including real estate finance, loans, leverage finance, debt capital markets, securitization, structured products, repos, derivatives and financial regulatory and compliance. Naina has been actively involved in the creat...ion of innovative award winning structured transactions and negotiating complex financings. She has advised global institutions such as Credit Suisse, Citigroup and Goldman Sachs and spent many years practicing law at Allen & Overy, Linklaters and Sidley Austin Brown & Wood in multiple jurisdictions including London, New York, Hong Kong and Singapore. Naina holds a Law LL.B (Hons) degree from University College London and has worked in the Finance Know-how team at Clifford Chance. She is also an author and runs her own business consultancy.
Juan Ramirez
Juan Ramirez is a derivatives and bank capital expert with more than 20 years of front-office experience across derivatives sales and trading, market risk, and regulatory capital. He has held senior roles at J.P. Morgan, Lehman Brothers, Barclays, Santander, and BNP Paribas. Juan is currently a Senior Bank Regulatory Capital Specialist at Barcl...ays in London. He previously worked at Deutsche Bank London as a Market Risk Capital (FRTB) expert, bringing together deep front-office derivatives experience with specialist expertise in the evolving regulatory framework for market and bank capital. He is the author of several books on derivatives, capital markets, and bank capital, including Accounting for Derivatives, Handbook of Corporate Derivatives and Equity Capital Markets, Handbook of Basel III Capital, Basel IV Market Risk Capital, and FRTB – Fundamental Review of the Trading Book (IMA). Juan holds a BSc in Electrical Engineering from ICAI in Spain and an MBA from the University of Chicago.
Wim Schoutens
Prof Wim Schoutens is Research Professor in financial engineering in the Department of Mathematics at the Catholic University of Leuven, Belgium. He has extensive practical experience of model implementation and is well known for his consulting work in the banking industry. Wim is also the author of Lévy Processes in Finance: Pricing Financial D...erivatives and co-editor of Exotic Option Pricing and Advanced Lévy Models both published by Wiley. He is also co-author of "The Handbook of Convertible Bonds" and "The Handbook of Hybrid Securities" (Wiley). His research interests cover all areas of financial mathematics, and recent publications cover jump driven credit models as well as equity models, model risks, hedging of exotics and multivariate financial modelling. Wim is also an independent expert advisor to the European Commission (DG-Competition) on “State aid assessment of valuation of impaired assets and of asset relief measures” and is a Managing Editor of the International Journal of Theoretical and Applied Finance and Associate Editor of Mathematical Finance and Review of Derivatives Research. Wiley Finance Published Author.
Tony Sims
Dr Tony Sims is an experienced educator and consultant specialising in the teaching and application of mathematical and quantitative methods. He has more than 20 years of experience delivering university-level teaching, professional courses, and management development programmes. Tony was formerly MBA Course Director at Kingston University Busin...ess School and has extensive experience teaching mathematical methods to students and professionals at all levels. Alongside his academic work, he has worked on consulting projects involving financial model development for businesses, giving him practical experience in applying quantitative methods to real-world financial problems. He is particularly recognised for his ability to explain complex mathematical and quantitative concepts clearly and effectively to audiences without a technical or quantitative background.
Jan De Spiegeleer
Dr Jan De Spiegeleer is a co-Founder of RiskConcile a risk management advisory firm based in Lausanne. From 2007 till 2015 he was the head of risk management at Jabre Capital Partners, a Geneva-based hedge fund. Jan gained extensive knowledge of derivatives pricing, hedging and trading while working for KBC Financial Products in London, where he... was managing director of the equity derivatives desk. He also ran his own market neutral statistical arbitrage hedge fund (EQM Europe) after founding Erasmus Capital in 2004. Jan holds a Masters Degree in Civil Engineering (Royal Military Academy- Brussels - Polytechnic Division – 1988), an MBA (KU Leuven – 1994) and a PhD in mathematics (KU Leuven – 2013).
Andreas Steiner
Andreas Steiner is an independent investment analytics consultant and Managing Director of Andreas Steiner Consulting GmbH, an investment analytics boutique he has operated since 2011. His work focuses on investment process design and implementation, including risk management, portfolio construction, performance analysis, and bespoke risk assessmen...t. Previously, Andreas held senior investment risk and performance management roles at Credit Suisse Asset Management, Rothschild Bank AG, and LGT Capital Management, where he was Head of Investment Risk Management. He has also taught portfolio management, performance analysis, international investing, behavioural finance, and investment processes as an external lecturer at Zurich University of Applied Sciences. Andreas has published research on a range of investment topics, including “Risk Parity for the Masses” in the Journal of Institutional Investing, and is the author of Essays on Applied Portfolio Analytics – Quantitative Methods for Investment Professionals, scheduled for publication in 2026/27. He is also Senior Strategic Advisor to the Global Security Fund at Finserve Nordic AB and holds a master’s degree (lic. oec. publ.), magna cum laude, in Economics from the University of Zurich.
Rupesh Tailor
Rupesh Tailor is a banking and investment specialist with more than 26 years of experience across leading sell-side and buy-side financial institutions, including Goldman Sachs, Barclays Capital, Merrill Lynch, Auriga Investors, Morgan Stanley, and Nordea Asset Management. His expertise spans bank asset and liability management (ALM), capital a...nd liquidity management, ICAAP and ILAAP stress testing, and the analysis and management of investments across high yield, leveraged finance, and distressed debt. He has extensive experience across credit and equity markets, including analysis, trading, and portfolio management. Rupesh has advised major European banks on stress-testing and regulatory capital requirements, including work related to the 2014 European Central Bank and European Banking Authority stress test of euro-area banks. He has also developed proprietary stress-testing models for banks and institutional investors, with a particular focus on identifying financial vulnerabilities and businesses in structural decline at an early stage. He holds a First Class MA in Economics from the University of Cambridge.
- Strategic Asset Liability Management
- Bank Stress Testing
- Convertible Bonds: Issuing, Pricing and Investing
- Distressed Debt Investing
- Fixed Income Attribution
- Advanced Bank Liquidity Management
- Volatility: Trading and Managing Risk
- Credit Products and Derivatives
- Equity Derivatives
- Equity Derivatives 2: Exotics and Structures
- Commodity Markets & Derivatives: Trading & Managing Risk
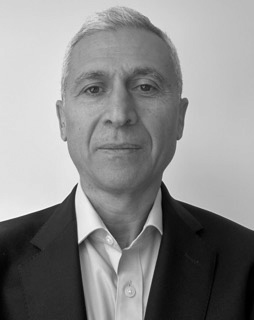
Birol Unal
Dr Birol Unal is a capital markets and quantitative finance expert with more than 25 years of experience spanning quantitative valuation, risk management, front-to-back trading business oversight, and business transformation at leading global investment banks. He began his banking career in 1999 at Credit Suisse First Boston in the Quantitative... Valuations Group within Finance. In 2003, he joined Morgan Stanley, where he led the Global Fixed-Income Model Control Group and subsequently served as European Business Unit Risk Manager. He moved to UBS in 2009, where he held a series of senior roles, including Operating Officer for the Global Structured Rates Desk and Co-Operating Officer for the Global Rates and Credit business. Most recently, he led the Business Analysis team within the UBS Investment Bank Change division. Birol holds a PhD in Quantitative Finance from Imperial College London, as well as an MSc and BSc in Electrical and Electronics Engineering from Imperial College London and Middle East Technical University, Ankara, respectively.
Jean-Luc Verhelst
Jean-Luc Verhelst is the author of the book Bitcoin, the Blockchain and Beyond (2017) and a renowned public speaker, trainer and advisor on blockchain. He teaches at multiple universities and training centers in Europe and the Middle East and advises corporates on their blockchain journey through workshops and advisory. Prior to his current posi...tion, he worked several years as a strategy consultant and became the blockchain leader for Deloitte Belgium after having spent several months at Deloitte’s EMEA Blockchain Lab. He worked for numerous clients in Europe, managed the development of blockchain solutions, and delivered internal trainings in EMEA and the USA. He also co-founded blockchain communities, was selected by the European Commission as a member of the EU Blockchain Observatory and Forum and won the world’s largest blockchain hackathon of 2016. His master thesis on Bitcoin received the award for best financial thesis of 2014 in Belgium. Jean-Luc holds academic degrees in IT and business. Most importantly, Jean-Luc has a real passion for blockchains and how they will shape our future.
Uwe Wystup
Dr Uwe Wystup is an expert in foreign exchange derivatives and quantitative finance, combining extensive industry experience with a distinguished academic career. He is Managing Director of MathFinance AG, Professor of Financial Option Price Modeling and Foreign Exchange Derivatives at the University of Antwerp, and Honorary Professor of Quantitati...ve Finance at Frankfurt School of Finance & Management. Uwe has worked in FX derivatives since 1992, holding senior roles at Citibank, UBS, Sal. Oppenheim and Commerzbank. He is also a Public Expert on Currency and Interest Rate Management for the Chamber of Commerce and serves as a judge at the Financial Court and Commercial Court in Germany. He holds a PhD in Mathematical Finance from Carnegie Mellon University. Uwe is the author of Foreign Exchange Risk, first published in 2002 and translated into Mandarin, and FX and Structured Products, now in its second edition. He has published extensively in academic journals and writes the FX Column for Wilmott magazine.
Don't just take our word for it
What our clients say:
Rupesh is an excellent teacher. He offered lots of practical exercises and a clear explanation of the topic [Advanced Bank Liquidity Management].
Transaction Management Analyst, European Investment Bank
"The London Financial Studies (LFS) course was very enlightening and practical. The professor showed exceptional professionalism and mastery of the course topics. I will encourage every financial organization to consider LFS for their in-house courses.''
Consultant, The World Bank
"Wonderful group of people at LFS - efficient, professional and dedicated to you for the duration of your course. I was particularly impressed with the curation of a reading list available to all those that sign up for a course - something you have access to for up to a year following your course date!''
Quantitative Developer, Royal Bank of Scotland
"LFS was professional in organising and providing the right lecturers with relevant practical experience.''
Risk Manager, IFC
"As a regulator, I highly recommend this course. The content and examples will be very useful in performing our jobs.''
James, Federal Reserve Bank of New York
"The Capital Markets, Fixed Income, and Interest Rate Derivatives course with Richard Fedrick was genuinely the BEST class I have ever taken. I enjoyed the broad but somehow very detailed overview of the topics and learned an incredible amount. Richard has a gift for teaching and was able to explain difficult topics very clearly. All of the course material is directly applicable to my work. The LFS course was delivered in a way that worked very well in the virtual format.''
Financial Analyst, The World Bank
"The course met all of my expectations and much more! The course content was quite accessible and offered excellent coverage of bilateral margining and central clearing with real life applications and examples. Highly recommend it!''
Specialist, OSFI
"LFS is the best. Front edge and great instruction!''
Peter, FDIC
"Great course with a very skillful and communicative tutor. It exceeded my expectations and strengthened my knowledge of the subject in a short time.''
Risk Manager, Banca d'Italia
Head Office
34 Curlew Street
Butlers Wharf
London SE1 2ND
Contact
EMEA: +44 (0) 20 7378 1050
Americas: +1 212 710 1343
Asia Pacific: +65 3159 3707
© Copyright London Financial Studies 1997 – 2024